Estate Planning Attorney Guide for Protecting Your Family in 2026
Estate planning has become increasingly important as families manage diverse assets, changing relationships, and new forms of digital wealth. A modern estate may include a home, retirement accounts, investments, business interests, rental properties, insurance policies, cryptocurrency, and other digital assets.
Creating an effective plan involves more than deciding who receives property. It can also involve preparing for incapacity, organizing financial information, coordinating beneficiary designations, and considering how assets should be managed in the future. An estate planning attorney can help individuals understand their options and develop a plan that reflects their circumstances and long-term objectives.
Why Estate Planning Matters in 2026
Financial and family circumstances rarely remain unchanged for long. People may marry, divorce, have children, purchase property, start businesses, receive inheritances, or experience significant changes in wealth.
Technology has also transformed the way people own and manage assets. Digital investment accounts, cryptocurrency, online businesses, websites, and intellectual property can now form part of an individual's financial picture.
These changes make regular estate planning reviews increasingly valuable. A plan that was appropriate several years ago may no longer address current assets or family priorities.
Begin With a Complete Asset Inventory
Understanding what you own is one of the first steps toward creating an organized estate plan.
An asset inventory can include real estate, bank accounts, investment portfolios, retirement accounts, life insurance policies, business interests, valuable personal property, and digital assets.
Important ownership records should be kept securely and updated when significant financial changes occur.
An accurate inventory can also make future administration easier because family members or fiduciaries can more readily identify the property that needs attention.
Review Beneficiary Designations
Beneficiary designations are an important part of many financial plans. Retirement accounts and insurance policies commonly allow individuals to identify who should receive the proceeds.
These designations should be reviewed after major life events such as marriage, divorce, remarriage, the birth of a child, or the death of a beneficiary.
It is also important to consider whether beneficiary designations remain consistent with the overall estate plan. Different documents and accounts should be reviewed together rather than in isolation.
Don't Forget Digital Assets
Digital property deserves greater attention in modern estate planning.
Cryptocurrency, online investment accounts, websites, domain names, digital businesses, intellectual property, and other electronically stored assets can have significant financial value.
Without appropriate records, these assets may be difficult for family members to locate or manage.
Individuals should consider maintaining a secure inventory of important digital property and relevant ownership information. Passwords and authentication credentials should be protected carefully to balance security with appropriate future access.
Prepare for Incapacity
Estate planning is not limited to what happens after death. An unexpected illness or injury could prevent someone from managing financial or personal affairs.
Preparing appropriate legal documents in advance can provide direction regarding who may handle certain responsibilities when an individual cannot act independently, subject to applicable law.
This type of preparation can be especially important for business owners, individuals with substantial investments, and anyone with complex financial responsibilities.
Planning ahead allows people to communicate their preferences while they are able to make informed decisions.
Consider Business Succession
Business owners should think carefully about what happens to their company if they retire, become incapacitated, or die.
A closely held business may represent a significant portion of a family's wealth. Without a succession strategy, uncertainty can arise over ownership, management, and control.
Potential successors, ownership transfers, management responsibilities, and the interests of family members or business partners should be evaluated early.
Business succession planning can also help prepare the next generation for the responsibilities associated with managing an established company.
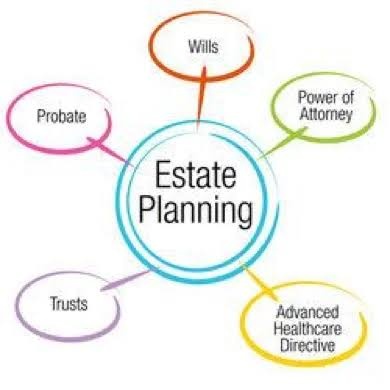
Understand the Role of Trusts and Wills
Wills and trusts can serve different purposes within an estate plan.
A will can communicate instructions concerning the distribution of assets after death and may address other matters permitted by applicable law. Certain trusts can provide ongoing asset management during an individual's lifetime or after death.
The appropriate structure depends on factors such as the individual's assets, family circumstances, financial goals, and applicable legal requirements.
Rather than selecting a planning tool simply because it is popular, individuals should consider how each option fits into their complete financial picture.
Keep Estate Documents Organized
An estate plan is more effective when important documents can be located easily.
Legal documents, financial statements, insurance records, property information, tax documents, business records, and other important materials should be stored securely and systematically.
Digital copies can provide additional protection, but confidential information should be protected with appropriate security measures.
Trusted individuals should know where essential records are located and who to contact when assistance is required.
Review the Plan After Major Life Events
One of the most important reasons to revisit an estate plan is that life changes.
Marriage, divorce, retirement, relocation, inheritance, the birth of a child, a business acquisition, or significant changes in assets can all affect existing arrangements.
Changes in laws may also make a professional review worthwhile.
Regular reviews can help identify outdated beneficiary designations, missing assets, inconsistent documents, or other issues before they become difficult to address.
How Professional Guidance Can Help
Estate planning can become complicated when an individual owns multiple properties, substantial investments, business interests, digital assets, or has a blended family.
An estate planning attorney can help explain available planning options, review existing documents, identify potential gaps, and coordinate different parts of an estate plan.
Professional guidance can be particularly useful when several legal and financial considerations need to work together.
The objective should be to create a practical plan that reflects the individual's goals without adding unnecessary complexity.
Estate Planning Is an Ongoing Process
Creating an estate plan should not be viewed as a one-time task. Financial circumstances, family relationships, laws, and personal priorities can all change over time.
A regular review schedule can help individuals keep documents and financial records current.
Technology also makes organization easier through digital recordkeeping and financial management tools, although security and privacy should remain priorities.
A flexible approach allows an estate plan to evolve as circumstances change.
Conclusion
Estate planning provides an opportunity to make important financial and family decisions before they become urgent. By organizing assets, reviewing beneficiary designations, addressing digital property, preparing for incapacity, considering business succession, and keeping documents current, individuals can create greater clarity for themselves and their loved ones.
Working with an estate planning attorney can provide valuable guidance when legal, financial, and family considerations become complicated. Ultimately, the strongest estate plan is one that reflects current circumstances, remains adaptable, and clearly supports the individual's long-term goals.
About Premium Author
This post has been authored and published by one of our premium contributors, who are experts in their fields. They bring high-quality, well-researched content that adds significant value to our platform.
Popular Categories
Stay Connected
Recent Posts